Corporate Bitcoin treasury acquisitions are accelerating faster than most analysts predicted, and the two names driving the bulk of the action — Strategy and Strive — are doing it in ways that reveal fundamentally different philosophies about how to build a Bitcoin war chest.
Strive’s $335 Million Sprint Changes the Corporate Leaderboard
Let’s start with the number that actually surprised me this week. Strive has accumulated 36,818 BTC after executing three major purchases in the span of eight days — a pace that’s aggressive even by the standards of this bull cycle. The most recent tranche was 1,223 BTC acquired for roughly $100 million, with The Block reporting an average cost basis of around $81,734 per coin. That’s not a screaming bargain at current prices, but it’s not reckless either — BTC is trading around $81,500 right now, so Strive is essentially buying at spot with minimal slippage, which tells you they have decent execution discipline.
What’s more interesting is the financing structure behind this buying spree. According to Decrypt, warrant holders exercised positions that brought in $369 million, and the company is now planning a $630 million sale of 15% preferred stock. That preferred stock yield is not cheap capital. Fifteen percent is the kind of rate you pay when your equity story is still being established and institutional money wants a floor. It works as long as Bitcoin appreciates faster than the cost of that capital — which, historically, it has — but it introduces real fragility if we get a prolonged drawdown.
The acquisition pushed Strive past MARA Holdings on the corporate BTC leaderboard, which is a milestone worth noting even if league tables aren’t the point. The point is that a relatively young Nasdaq-listed company has built a 36,000+ BTC position at speed using equity markets as a funding engine. CryptoPotato noted this as a milestone moment for the firm, and I’d agree — though milestones don’t protect you from a bear market.
Strategy Is Playing a Different Game Entirely
Meanwhile, Strategy’s October buying has been more measured — methodical even. Bitcoin Magazine reported that this was Strategy’s third purchase of the month, bringing October spending to $73 million total. The latest add was just 267 BTC for $22 million — which, on an 848,517 BTC portfolio, is essentially rounding-error territory. But Saylor does this deliberately. The weekly buys, the Sunday hints on social media before Monday announcements (a pattern CryptoPotato flagged), the Saylor quote “we found room for more orange” — it’s all part of maintaining a narrative of relentless accumulation as much as it’s about the Bitcoin itself.
The more structurally significant move this week wasn’t the BTC buy. It was Strategy raising its preferred stock buyback authorization to $3 billion and then actually spending $193.1 million repurchasing STRC shares while discretionary cash dropped to $447.3 million — a 72% decline, as CryptoSlate highlighted. That’s a company actively managing its capital structure, not just hoarding Bitcoin. Strategy now holds 848,517 BTC bought at an average of $75,446, sitting on roughly $5.9 billion in unrealized gains — which accounts for about 4% of total bitcoin supply. That’s not a treasury position. That’s a geopolitical-scale accumulation event dressed up in corporate filings.
The STRC buyback is worth unpacking separately. When a company aggressively buys back its own preferred shares while also buying Bitcoin, it’s simultaneously reducing dilution risk and doubling down on the core thesis. It’s a confident move. It also burns cash at a rate that would terrify a conventional CFO. Strategy’s discretionary cash cushion is now thin enough that one bad quarter of equity market access could force a very uncomfortable conversation.
Why the Capital Stack Matters More Than the BTC Count
Here’s where I want to push back on the framing most crypto media uses when covering these stories. The headline number — 36,818 BTC for Strive, 848,517 for Strategy — isn’t really the story. The story is how each company is financing those positions and what the liability side of their balance sheet looks like.
Strategy’s average cost basis of $75,446 means it has a reasonable cushion at current prices. Its structure, while complex, is well-established with institutional investors who understand the model. Strive, by contrast, is paying 15% on preferred stock while acquiring BTC at $81,734 average. That spread needs to widen significantly — or stay positive — for the math to work over a three-to-five-year horizon. If Bitcoin hits $150,000+, both companies look like geniuses. If we chop sideways at $70,000 for eighteen months, Strive’s cost of capital becomes a serious problem while Strategy’s lower basis gives it more room to breathe.
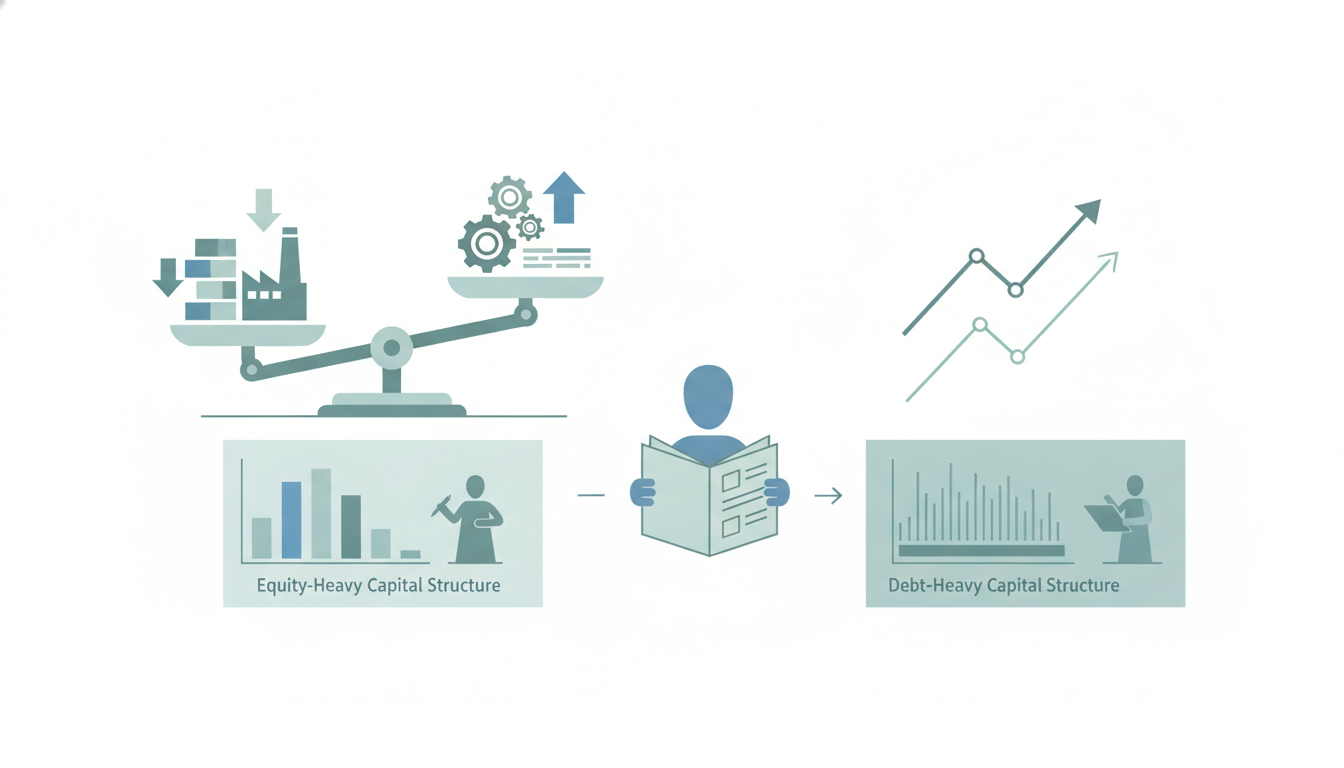
This is why I track crypto treasury developments differently from regular price news. These aren’t trades. They’re structured bets with embedded leverage and maturity profiles, and the risk isn’t just directional Bitcoin risk — it’s refinancing risk, dilution risk, and narrative risk all wrapped together.
For traders looking to get exposure to these moves without the corporate balance sheet complexity, understanding where to trade with lower fees matters. You can check current exchange referral offers to reduce friction costs if you’re actively positioning around BTC price action driven by these accumulation events.
My Take: The Model Works Until It Doesn’t, and We’re Closer to the Stress Test Than People Think
I’ve watched enough cycles to know that corporate Bitcoin treasury strategies look brilliant in a bull market and catastrophic in a prolonged bear. The Strategy playbook specifically has survived one serious test — the 2022 drawdown — and Saylor emerged with the thesis intact. That earns real credibility. But the number of imitators running thinner margins with higher cost capital is growing, and Strive’s aggressive preferred stock issuance at 15% is exactly the kind of structure that blows up when sentiment shifts.
My honest read: Strategy is in a category of its own, with enough scale, institutional buy-in, and average cost basis to weather most scenarios short of a catastrophic Bitcoin collapse. Strive is a more speculative proposition — high conviction, aggressive execution, but financing costs that require Bitcoin to perform. If you’re trading MSTR or adjacent equities, the STRC buyback news is quietly bullish for share structure. If you’re watching Strive as a proxy bet on BTC upside, understand that it’s more levered than the headline BTC count implies. Neither of these is a passive Bitcoin ETF. Treat them accordingly.
Popular Exchange Referral Codes
- Bybit Referral Code 2026: Get 20% Fee Discount for 90 Days with Code 19670
- Bitget Referral Code 2026: Get 20% Trading Fee Discount with Code t4685009
- OKX Referral Code 2026: Get 20% Trading Fee Discount with Code 64912533
- HTX Referral Code 2026: Get 20% Trading Fee Discount with iddq7223
- Gate.io Referral Code 2026: Get a 20% Trading Fee Discount with Code NZRAPCBW
